Uncategorized Income: What It Means and How to Fix It
Uncategorized income usually means money recorded in an accounting or bookkeeping system without being assigned to the correct income account. It is often a temporary holding category rather than a true type of income.
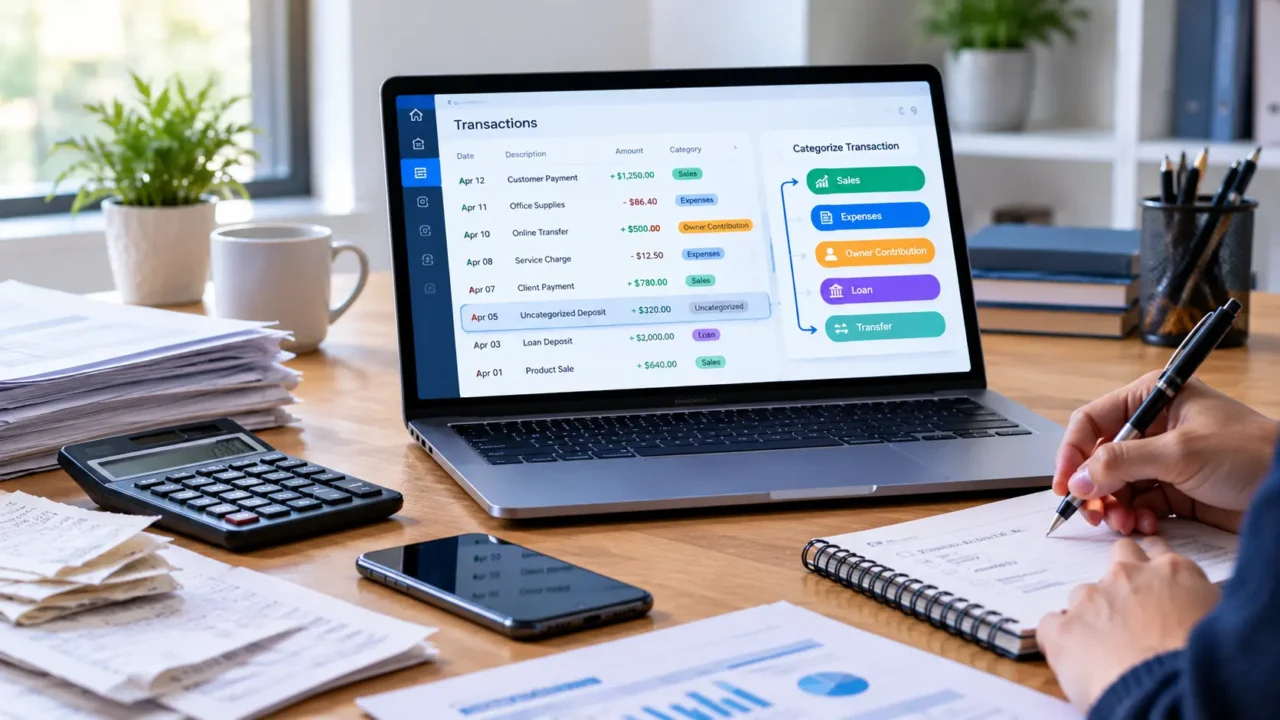
This commonly happens when a bank transaction is imported into bookkeeping software and the system cannot determine where the deposit belongs. In QuickBooks, for example, amounts received that cannot be assigned to a specific account may appear under Uncategorized Income.
The important point is simple: do not assume every transaction labelled “Uncategorized Income” is actually business income. It could be a customer payment, owner contribution, loan proceeds, transfer, refund, or another type of transaction. You need to identify the source before assigning the correct account.
Note: Tax rules vary by country and business structure. The tax discussion below uses U.S. federal rules as an example and is not a substitute for advice from a qualified tax professional.
What Is Uncategorized Income?
Uncategorized income is a bookkeeping label used when a received transaction has not yet been assigned to an appropriate account.
For example, suppose a business receives a $1,000 bank deposit. The accounting software sees the deposit but cannot determine whether it represents:
- Product sales
- Service revenue
- A customer invoice payment
- A loan
- An owner contribution
- A refund
- A transfer from another account
- Another type of receipt
Instead of leaving the transaction without an account, the software may temporarily place it in an uncategorized account.
QuickBooks documentation and support discussions show that downloaded bank transactions can be reviewed, matched and assigned to the appropriate category or account.
Is Uncategorized Income Really Income?
Not necessarily.
This is one of the most important things to understand.
The word “income” in the account name does not automatically determine the tax or accounting treatment of the transaction.
Consider this example:
| Bank deposit | Possible accounting treatment |
|---|---|
| Customer paid an invoice | Sales or service income |
| Owner put personal money into the business | Owner contribution/equity |
| Business received a loan | Loan liability |
| Money moved between business bank accounts | Transfer |
| Customer refund received from a supplier | Depends on the underlying transaction |
| Interest received | Interest income |
| Unknown deposit | Investigate before categorizing |
The correct treatment depends on what the money actually represents.
Why Does Uncategorized Income Appear?
There are several common reasons.
Bank Feeds Cannot Identify the Transaction
When financial transactions are downloaded into bookkeeping software, the available bank description may not contain enough information to identify the correct account.
QuickBooks notes that bank transaction information depends partly on the information supplied by the financial institution, including payee names and descriptions.
A New Customer Made a Payment
A new customer may send money before the accounting system has enough information to connect the payment with an existing invoice.
A Transaction Was Added Manually
Someone may have accepted a deposit without choosing the correct income account.
The Transaction Was Not Matched
A bank deposit may already have been recorded through an invoice or sales receipt. If the downloaded bank transaction is added again instead of matched correctly, it can create duplicate or misleading income records.
QuickBooks recommends reviewing possible matches before adding downloaded transactions.
The Source Was Unclear
A business owner may simply postpone categorizing an unusual deposit until more information is available.
That can be reasonable temporarily, but leaving transactions unresolved for months can make bookkeeping and reporting more difficult.
How to Fix Uncategorized Income
The safest approach is to investigate each transaction individually.
Review the Transaction
Start with the basic information:
- Date
- Amount
- Bank description
- Payee or sender
- Reference number
- Related invoice
- Payment processor
- Notes or memo
Do not categorize the transaction based only on the amount.
Identify Where the Money Came From
Ask:
Who sent this money, and why?
Check your:
- Invoices
- Sales records
- Contracts
- Emails
- Payment processor records
- Bank statements
- Loan documents
- Owner contribution records
For recurring business payments, this information is often enough to identify the correct account.
Check for an Existing Transaction
Before adding the deposit as new income, check whether you already recorded it.
For example, imagine you entered a $2,500 customer payment when an invoice was paid. Later, the $2,500 bank transaction appears in the bank feed.
Adding it as new income could potentially count the same payment twice.
Matching the bank transaction to the existing record is generally preferable when the match is correct. QuickBooks provides matching tools for this purpose.
Choose the Correct Account
Once you understand the transaction, assign it to the appropriate account in your chart of accounts.
For example:
- Consulting payment → Consulting Revenue
- Product sale → Product Sales
- Interest received → Interest Income
- Owner contribution → Appropriate equity account
- Loan proceeds → Appropriate loan liability account
- Transfer → Corresponding bank or asset account
Do not create a new account every time you encounter an unusual deposit. Keep the chart of accounts practical and consistent.
Keep Supporting Documentation
Save evidence that explains unusual transactions.
Useful records may include:
- Invoices
- Receipts
- Contracts
- Bank statements
- Loan agreements
- Payment confirmations
- Emails
- Transaction notes
This makes future bookkeeping much easier.
How Uncategorized Income Affects Financial Reports
Leaving transactions unresolved can make financial reports harder to understand.
For example, imagine a business has:
- $80,000 in properly categorized sales
- $10,000 in Uncategorized Income
The owner may see $90,000 associated with income accounts, but the $10,000 does not explain what actually generated that money.
That makes it harder to answer questions such as:
- How much did we earn from services?
- How much came from product sales?
- How much was investment income?
- Was part of the money actually a loan?
- Did the owner contribute money?
- Are sales increasing or decreasing?
Accurate categorization gives financial reports more useful information.
Uncategorized Income and Taxes
A bookkeeping label and a tax classification are not the same thing.
For U.S. federal tax purposes, the IRS states that gross income generally includes income from whatever source it is derived, subject to applicable exclusions. For businesses, the IRS also says business income generally includes income connected with the business and that income must be reported even when it was not reported on a Form 1099.
However, an unidentified bank deposit is not automatically a particular type of taxable business revenue simply because accounting software placed it in an account called “Uncategorized Income.”
You first need to establish what the payment represents.
For example, a business loan proceeds and a customer payment are both deposits into a bank account, but they are not the same type of transaction.
If you are unsure about the tax treatment of an unusual transaction, ask a qualified accountant or tax professional.
Uncategorized Income vs. Business Income
These terms should not be confused.
Business income describes money earned through business activities.
Uncategorized income describes a bookkeeping classification where the nature or account assignment has not yet been properly determined.
A transaction can start as Uncategorized Income and later become ordinary business revenue once you identify it.
Simple Example
A freelance designer receives $1,500.
At first, the bank feed cannot identify the payment, so the transaction appears under Uncategorized Income.
The designer checks the bank description and finds that the payment came from a client for an existing invoice.
The transaction can then be matched to the invoice or assigned to the appropriate service-revenue account.
The label has changed, but the underlying money has not.
How to Prevent Uncategorized Income
Cleaning up old transactions is useful, but preventing the problem is even better.
Keep Invoices and Payments Connected
Whenever possible, make sure customer payments can be matched to the related invoices.
Review Bank Feeds Regularly
Do not wait until tax season to review months of transactions.
A weekly or monthly review can make bookkeeping much easier.
Use Consistent Customer Names
Consistent naming makes it easier for accounting software and people to recognize recurring transactions.
Use Bank Rules Carefully
Accounting software may offer rules that automatically categorize recurring transactions.
Automation can save time, but review the rule before relying on it. Incorrect rules can repeatedly categorize transactions incorrectly.
QuickBooks provides bank-rule functionality for automatically categorizing recurring bank transactions.
Reconcile Your Accounts
Bank reconciliation helps compare your accounting records with your actual bank activity.
If the balances or transactions do not agree, investigate the difference rather than simply forcing the accounts to balance.
Common Mistakes to Avoid
Treating Every Deposit as Sales
A bank deposit does not automatically mean a sale.
It could be a transfer, loan, owner contribution, refund or another transaction.
Deleting Unknown Transactions
Deleting a transaction simply because you do not recognize it does not solve the underlying bookkeeping problem.
Investigate it first.
Creating Too Many Income Categories
A complicated chart of accounts can make bookkeeping harder.
Use categories that provide useful information without creating unnecessary complexity.
Ignoring Small Transactions
Small unexplained amounts can accumulate.
A regular review prevents a large cleanup project later.
Adding Bank Transactions Twice
If a transaction has already been recorded through an invoice, sales receipt or other entry, check for a match before adding the downloaded bank transaction.
A Simple Uncategorized Income Cleanup Checklist
Use this checklist when reviewing your books:
- List all uncategorized deposits.
- Check the date and amount.
- Identify the sender.
- Review invoices and payment records.
- Check whether the transaction already exists.
- Determine what the money represents.
- Assign the appropriate account.
- Attach or retain supporting documentation.
- Review for possible duplicates.
- Reconcile the bank account.
For larger or complicated bookkeeping problems, professional review can be worthwhile.
When Should You Ask an Accountant?
Consider professional help when:
- A large amount remains unexplained.
- You cannot determine the source of a transaction.
- The deposit could be a loan, investment, owner contribution or other non-sales transaction.
- You have already filed a tax return containing incorrect information.
- You have many duplicate or miscategorized transactions.
- Multiple businesses or bank accounts are involved.
- You are dealing with international transactions.
- The transaction has unusual tax consequences.
The IRS notes that businesses need books and records that clearly show their income and expenses for the relevant tax year.
Uncategorized Income FAQs
What does uncategorized income mean?
Uncategorized income generally means a received transaction has not yet been assigned to a specific income or other appropriate account in bookkeeping software. It is often a temporary classification rather than a distinct type of income.
Is uncategorized income taxable?
The label itself does not determine whether a transaction is taxable. You must first identify what the money represents and then apply the relevant tax rules. U.S. federal tax law generally includes income from many sources in gross income, subject to applicable exclusions.
How do I clear Uncategorized Income in QuickBooks?
Review the transaction, identify its source, check for an existing record or invoice, and then assign or match it to the appropriate account. QuickBooks provides tools for reviewing, matching and categorizing downloaded bank transactions.
Can a bank transfer be categorized as income?
Not automatically. A transfer between your own accounts is generally different from revenue from a customer. Identify the source and purpose of the transfer before categorizing it.
Should I delete Uncategorized Income?
Usually, the better approach is to investigate and correctly categorize or match the underlying transaction rather than simply deleting it. If the transaction is a duplicate or otherwise should not be recorded, follow the appropriate bookkeeping procedure.
How can I prevent uncategorized income?
Review bank transactions regularly, maintain accurate invoices and customer records, match payments correctly, and use carefully reviewed bank rules for recurring transactions.
Conclusion
Uncategorized income is usually a bookkeeping problem, not a special kind of income. It means a transaction has not yet been properly identified or assigned to the correct account. The solution is to investigate each deposit, check for existing records, determine what the money represents, and categorize or match it correctly. Regular bank-feed reviews, accurate documentation and careful reconciliation can prevent the problem from building up. If an unusual transaction could affect your tax return, get professional accounting or tax advice rather than guessing.